A major shift in New Zealand’s gas market is increasing uncertainty for manufacturers and other energy-intensive businesses, raising questions about energy availability and the resilience of supply chains that depend on domestic production.
Methanex plans to indefinitely idle its Taranaki production facilities in the first quarter of 2027 and sell all of its remaining contracted natural gas entitlements substantially through to the end of the decade.
The move will release gas into the domestic market but also remove New Zealand’s largest gas user and a source of flexibility that has previously redirected contracted supply to electricity generators during periods of increased demand.
New Zealand’s domestic gas production has continued to decline, while major users have adjusted consumption in response to tighter supply.
For businesses that rely on gas or electricity to maintain production, the transition puts greater focus on energy procurement, production continuity and the availability of domestic inputs across New Zealand’s supply chains.
Gas availability creates industrial supply chain risk
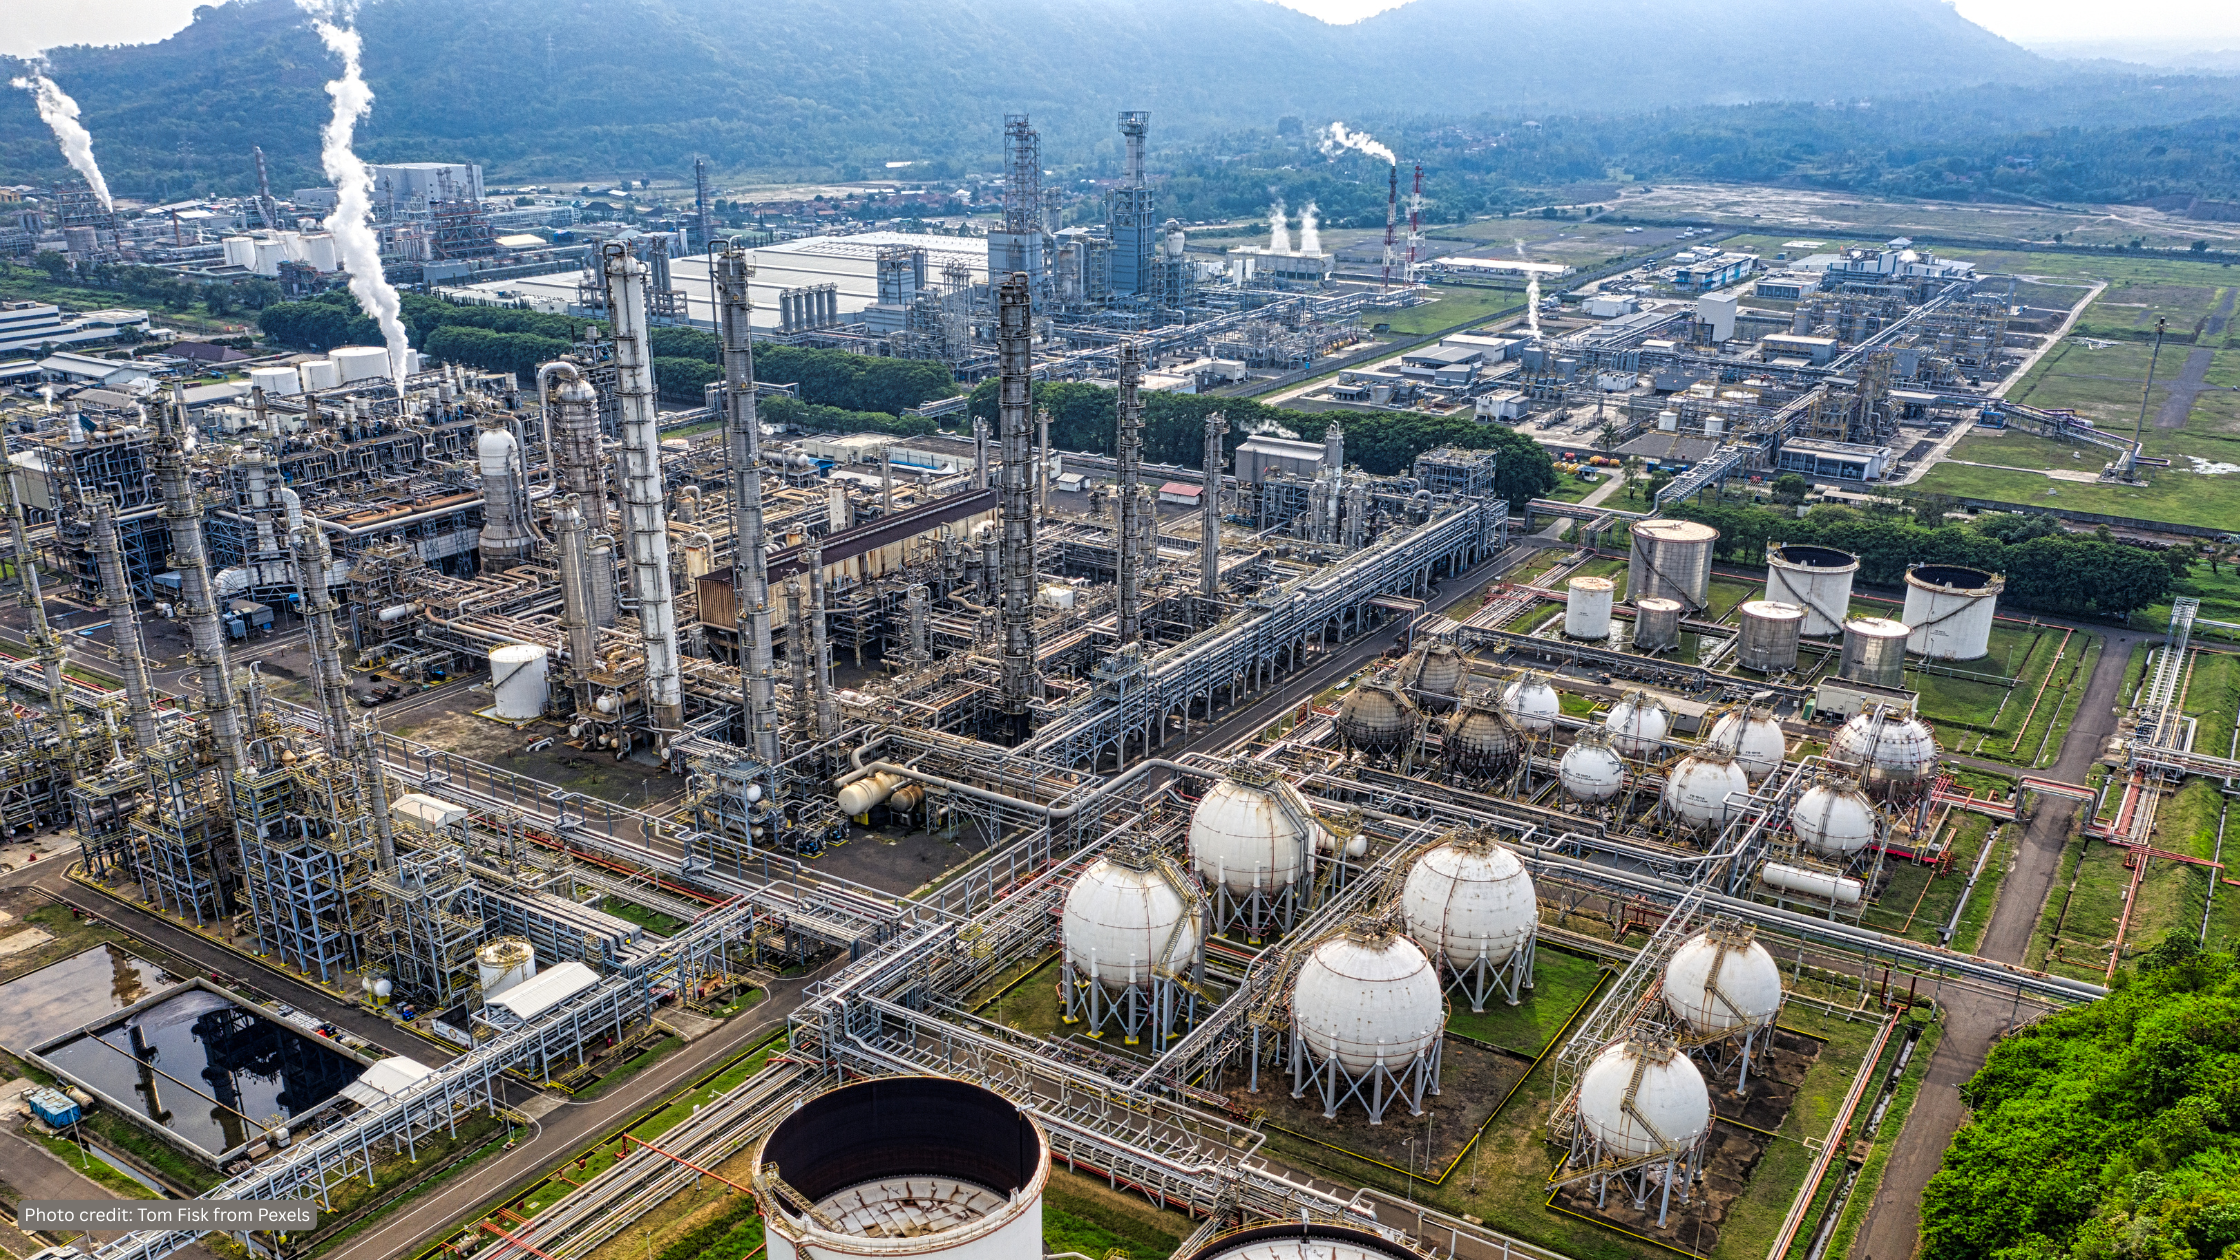
Natural gas supports a range of industrial activities in New Zealand, including chemical and fertiliser production, food processing and other operations requiring process heat. It also supports electricity generation when the power system requires additional thermal capacity.
That connects changes in the gas market with supply chains well beyond the energy sector.
Reduced or uncertain gas availability can affect manufacturers directly through production constraints and energy costs. Businesses further downstream can also face disruption when they depend on locally manufactured materials, agricultural inputs or other products.
Fertiliser production provides one example. Natural gas serves as an input at the Kapuni urea plant, meaning the availability of gas can influence domestic fertiliser production and, in turn, agricultural supply chains.
If domestic production falls, businesses may need to rely more heavily on imported alternatives, potentially increasing their exposure to international shipping, commodity prices and overseas supply disruptions.
Similar pressures can emerge across other energy-intensive industries where continuous access to energy supports production schedules and the availability of downstream goods.
Methanex exit reshapes gas allocation
Methanex has historically accounted for a substantial share of New Zealand’s natural gas consumption, using gas both as an energy source and as feedstock for methanol production.
Its scale has also allowed it to adjust production when other parts of the energy system require additional supply.
In 2024 and 2025, Methanex temporarily reduced or stopped production to make gas available for electricity generation. During the second quarter of 2026, another planned winter outage released gas for the electricity sector.
The company’s planned exit changes that relationship.
Selling its remaining contracted entitlements will make gas available to other users. However, the market will also lose a large industrial consumer that could reduce its own demand when electricity conditions tightened.
Some of that supply is already moving towards electricity generation.
Genesis Energy has secured approximately 11.4 petajoules of additional gas supply between March 2027 and December 2029 and has sought access to further Kupe gas for 2027 and 2028.
The transaction illustrates the redistribution likely to occur as gas previously contracted for methanol production becomes available to other parts of the economy.
For industrial supply chains, the key question is how the changing allocation of a declining resource affects both direct access to gas and the reliability and cost of electricity.
Industrial users seek greater market visibility
The changing supply picture has increased pressure for better information about future gas availability.
The Major Gas Users Group, which represents several large industrial consumers, supported greater access to basic market information during consultation on gas transparency.
Other market participants have questioned whether disclosure addresses the underlying supply problem.
Todd Energy argued during consultation that declining gas availability and reduced drilling represented the more fundamental challenge rather than a lack of information.
The different positions highlight two related issues for supply chain operators: whether enough energy will be available to maintain production and whether businesses have sufficient information to prepare for potential constraints.
The Ministry of Business, Innovation and Employment’s (MBIE) consultation with gas producers, electricity generators, industrial users and industry organisations found that participants considered information about future gas supply particularly valuable.
Transparency rules target major users
The Government is introducing new disclosure requirements as the market undergoes structural change.
The Gas (Market Transparency) Amendment Act 2026 created powers to require industry participants to disclose gas market information. Initial regulations will require large gas users and electricity generators to provide their gas supply agreements to MBIE.
The requirements aim to give regulators greater visibility over how gas is contracted as domestic supply declines and major users adjust their operations.
Better information could help identify emerging constraints earlier and provide a clearer picture of how available gas is distributed between industrial production and electricity generation.
However, greater transparency does not itself increase supply.
New Zealand recorded a 19.5 per cent year-on-year decline in net gas production in the June 2026 quarter, while gas use fell 20.4 per cent.
MBIE expects supply constraints to continue affecting gas use over the coming years.
Energy security becomes a supply chain issue
New Zealand’s changing gas market demonstrates how energy availability can become a broader supply chain constraint.
Manufacturers need reliable energy to maintain production, while agricultural supply chains depend on inputs produced by energy-intensive industries. Electricity generators also require gas at times when renewable generation cannot meet demand.
Changes in one part of the energy system can therefore flow through multiple supply chains.
Methanex’s planned exit will release contracted gas to other users, but it will also alter the way New Zealand balances industrial gas consumption with electricity generation.
The redistribution of available supply could benefit some users while leaving others more exposed to tightening availability, changing prices or competition for energy during periods of high demand.
Greater market transparency could give businesses more information for procurement, production and contingency planning, but New Zealand’s longer-term challenge remains the availability of energy itself.
For supply chain operators, the issue extends beyond the future of individual gas producers or consumers. It centres on whether manufacturers and other critical industries can maintain reliable access to energy and continue supplying the goods and inputs on which downstream businesses depend.
Read more: Fuel costs and weaker retail demand put pressure on Australian supply chains
Yvette is a Content Producer at Akolade, producing stories for Supply Chain Channel, an Australian learning ecosystem created to address the need for information, networking, case studies, and empowerment for everyone in the supply chain sector.