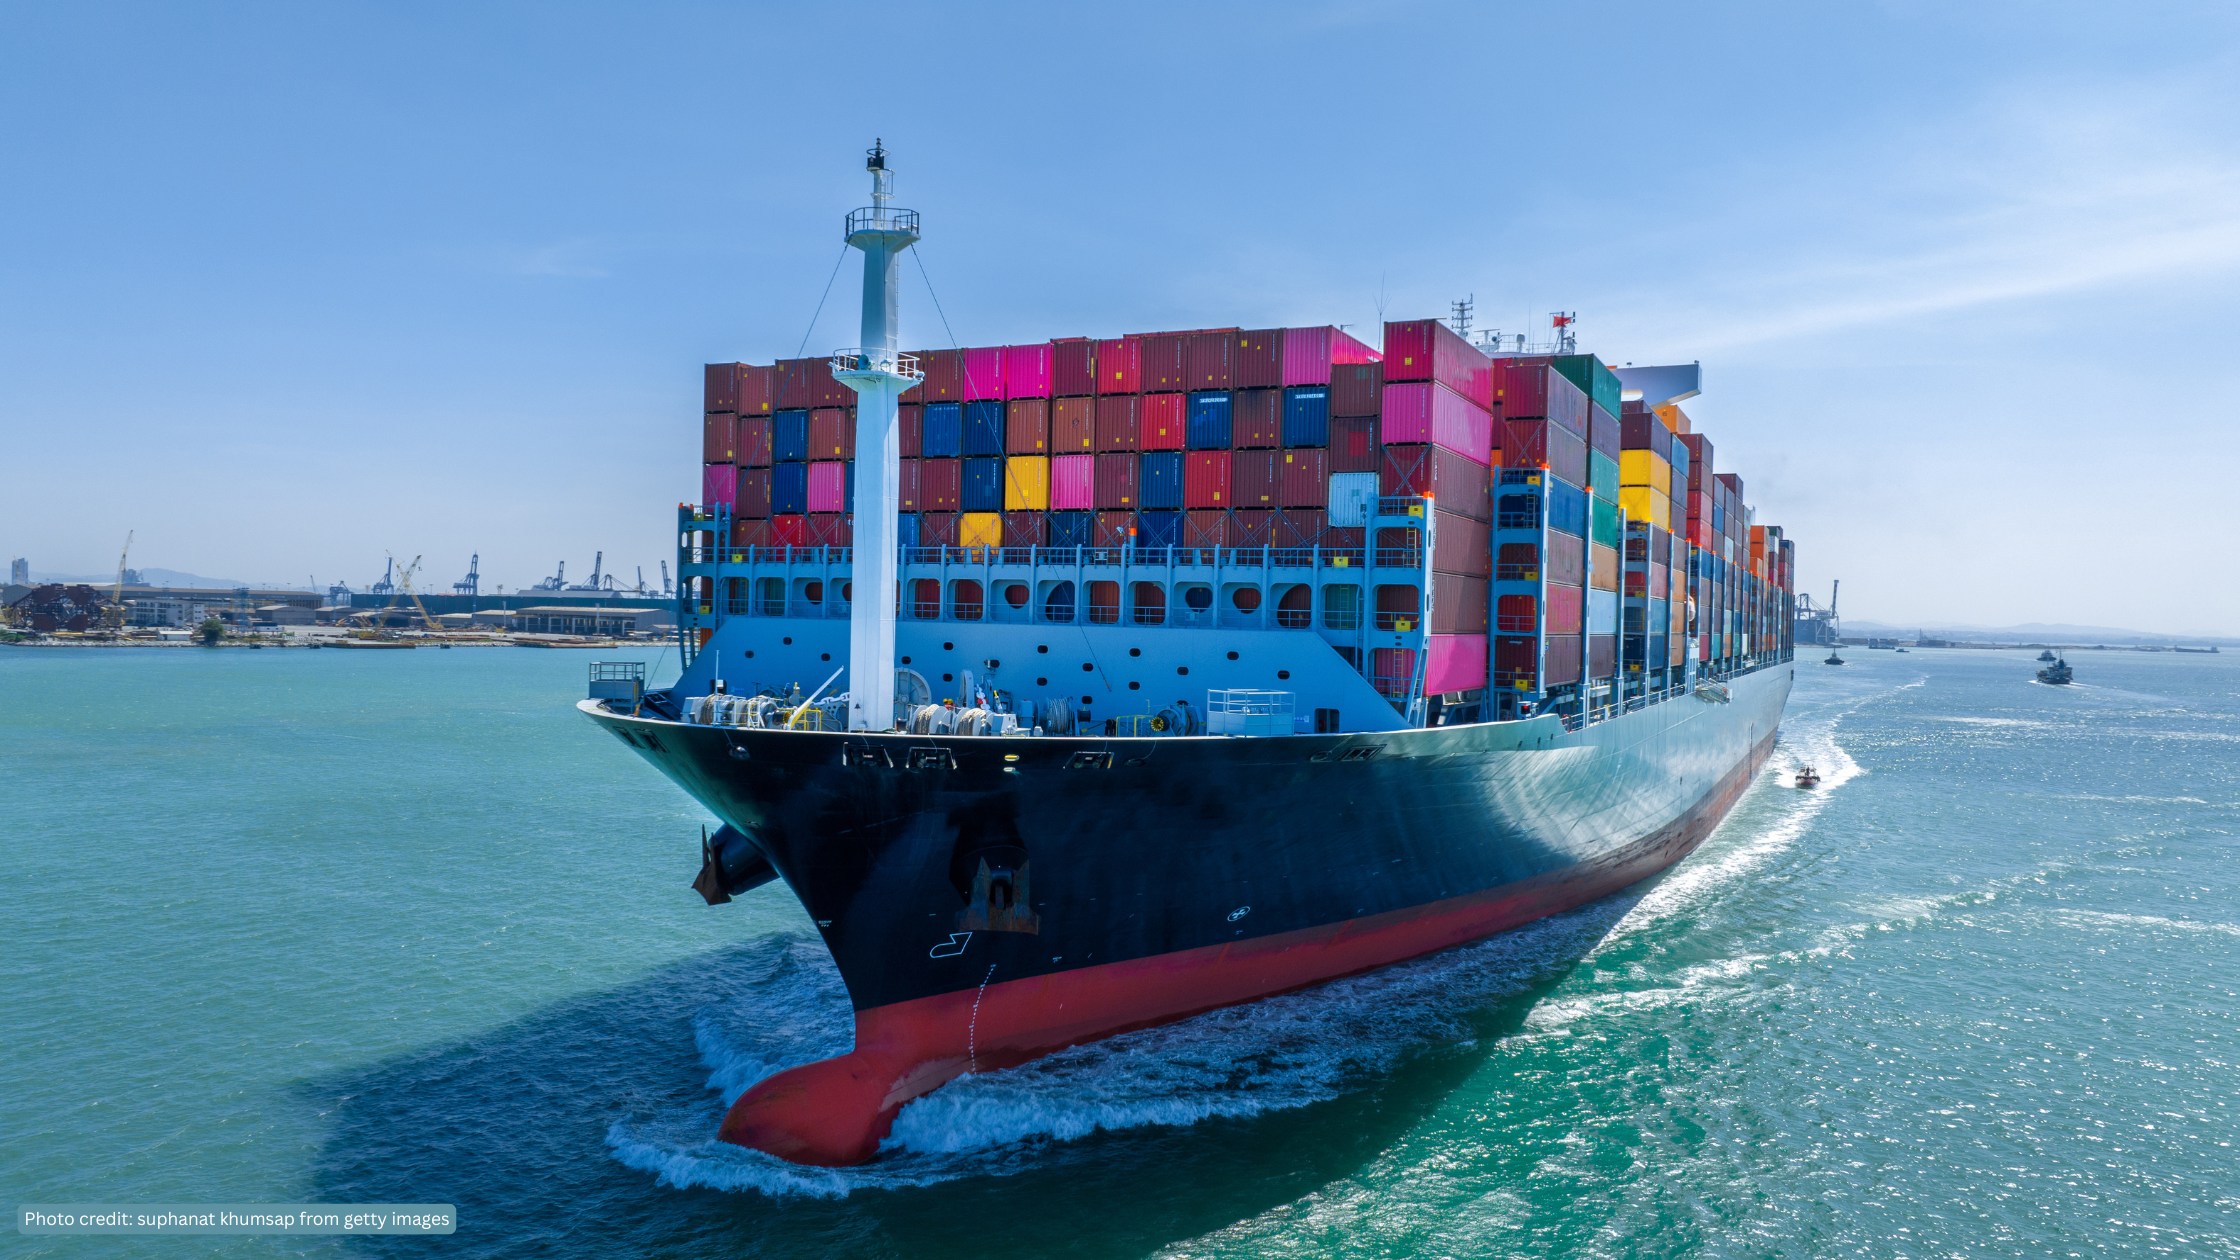
New Zealand’s transport and warehousing sector contracted in the June quarter as higher fuel costs increased pressure on freight operators, even as stronger exports continued to generate demand across supply chains.
Transport, postal and warehousing activity fell 1.7 per cent during the quarter, the largest downward contribution among the industries measured by Stats NZ. The decline was driven by lower road transport and transport support services activity.
The contraction came as diesel prices rose sharply and export volumes increased, highlighting the challenge freight operators face when demand for transport persists while the cost of providing that service increases.
Fuel costs increase pressure on transport
Fuel emerged as a significant cost pressure during the June quarter.
Diesel prices increased 47.7 per cent during the quarter and were 71 per cent higher than a year earlier, according to Stats NZ.
Prices for imported petroleum and petroleum products also rose 79 per cent compared with the March quarter, while petroleum import volumes fell 9 per cent.
Stats NZ said rising aviation fuel and diesel prices increased input costs for the air and road transport industries.
The increases followed international supply disruptions that began affecting domestic fuel prices earlier in the year.
For freight operators, fuel is a major component of the cost of moving goods, meaning rapid price increases can put pressure on margins or ultimately flow through to customers through higher freight charges.
Transporting New Zealand has also pointed to elevated operating costs across the road freight sector, while noting that freight demand has remained relatively resilient.
That creates a cost-to-serve challenge: businesses still need goods moved even when the cost of providing transport increases.
Export volumes continue to generate freight demand
The pressure on transport operators comes as New Zealand’s export supply chains remain active.
Total export volumes increased 3.3 per cent during the June quarter, according to Stats NZ.
Goods exports were a major contributor, with meat export volumes increasing 10.3 per cent. Other food, beverages and tobacco rose 7.2 per cent, while dairy exports also increased.
Stronger export volumes require products to move from farms and production facilities through domestic transport networks, storage facilities and ports before reaching international markets.
The figures therefore show that a decline in transport-sector activity does not necessarily mean freight requirements are disappearing across the economy.
Instead, different parts of the freight network can experience different demand and cost conditions at the same time.
Imports move in the opposite direction
Import volumes declined 0.8 per cent during the quarter, creating another point of difference between inbound and outbound supply chains.
Goods import volumes fell while their prices increased, with petroleum providing one of the clearest examples of the divergence between price and volume.
Changes in the balance between imports and exports can influence how freight capacity is used across ports, road networks and distribution facilities.
Retailers, wholesalers and manufacturers that depend on imported goods also remain exposed to changes in international transport, commodity prices and supply availability.
For logistics operators, this can create an uneven operating environment where volumes vary by customer, commodity and trade direction.
Freight-generating sectors show mixed conditions
Other parts of the economy also produced contrasting freight signals.
Construction increased 2.7 per cent during the quarter, the largest upward contribution to GDP, while wholesale trade grew 1.3 per cent.
Both sectors generate freight requirements through the movement of building materials, machinery, equipment and other goods.
Retail trade and accommodation, however, declined 1 per cent.
The different movements reinforce why headline GDP alone provides an incomplete picture of
freight demand.
New Zealand’s economy expanded 0.2 per cent during the quarter, but individual industries experienced considerably different conditions.
Cost-to-serve becomes a supply chain issue
For retailers, manufacturers, wholesalers and other freight customers, transport cost pressures extend beyond the logistics sector.
Higher freight costs can influence sourcing, inventory positioning, order frequency and the cost of serving customers across geographically dispersed markets.
Businesses may have limited ability to reduce freight requirements when products still need to reach stores, warehouses, factories, ports or customers.
This makes transport efficiency increasingly important, but efficiency alone cannot remove exposure to sharp changes in fuel and other operating costs.
The June-quarter figures illustrate that freight demand and freight-sector performance do not always move together.
Exports can increase and freight-generating industries can expand while transport operators simultaneously face weaker activity and substantially higher input costs.
For New Zealand supply chains, the challenge is therefore not simply maintaining the movement of goods, but doing so as the cost of providing that movement becomes increasingly difficult to predict.
Also read: Fuel costs and weaker retail demand put pressure on Australian supply chains
Yvette is a Content Producer at Akolade, producing stories for Supply Chain Channel, an Australian learning ecosystem created to address the need for information, networking, case studies, and empowerment for everyone in the supply chain sector.